

Use Form W-8BEN if you are a foreign individual receiving the income, and generally use Form W-8BEN-E if a foreign corporation is the beneficial owner. A US LLC, an EIN or a US-based game platform does not decide the form; your tax classification and ownership of the income do.
- For w8ben or w8ben e for game developers, choose by beneficial-owner status, not the platform’s location.
- Foreign individuals generally use W-8BEN; foreign corporations generally use W-8BEN-E.
- A foreign-owned US LLC does not automatically require W-8BEN-E or W-9.
- Corpulate suits non-resident founders seeking company formation, EIN, ITIN and tax compliance consulting.
Why this matters
Your platform's tax interview documents who receives the income and how the payer should handle US withholding. Selecting a business account does not automatically make you an entity for US federal tax purposes.
The wrong certification can produce incorrect withholding or a request for replacement documents. Resolve your ownership and classification before claiming treaty benefits.
Corpulate provides company formation and tax ID consulting for non-resident entrepreneurs. Those services address a different question from whether a particular game payment qualifies for reduced withholding.
W-8BEN or W-8BEN-E? Tax forms for non-US game developers
Start with the person or entity treated as owning the income for US tax purposes. The IRS calls that recipient the beneficial owner; an agent collecting money for somebody else is not necessarily that owner.
| Your situation | Usual documentation | Best fit | Main limitation |
|---|---|---|---|
| Foreign individual publishing personally | W-8BEN | Documenting an individual's foreign status | Does not document a separately classified corporation |
| Foreign corporation receiving its own income | W-8BEN-E | Documenting a foreign corporate beneficial owner | Requires entity and other applicable tax classifications |
| Foreign individual owning a disregarded US LLC | Generally the owner's W-8BEN | Documenting the foreign individual behind the LLC | Requires confirmation that the LLC is disregarded |
| US corporation receiving its own income | Generally W-9 | Certifying US-person status | Foreign shareholders do not make the corporation foreign |
| Foreign partnership receiving payments | Often W-8IMY with supporting documents | Documenting an intermediary or flow-through arrangement | Neither standard beneficial-owner form necessarily fits |
These are starting points, not permission to ignore exceptions. Effectively connected income, intermediary arrangements and special entity classifications require a separate assessment.
Official source for 2026 submissions: IRS, Instructions for Forms W-8BEN, W-8BEN-E, W-8IMY and W-9; recipient eligibility and beneficial-owner documentation.
W-8BEN: when you publish as an individual
W-8BEN generally fits a non-US individual who beneficially owns the payment. That includes a developer trading under a studio name without a separately classified corporation receiving the income.
For example, branding your releases under a studio label does not itself create a corporate taxpayer. Check the publishing contract and legal ownership rather than copying the name displayed on your store page.
Prepare the information the form requests:
- Legal identity: your individual name and citizenship information.
- Tax residence: the address and country relevant to your tax status.
- Tax identification: the foreign or US taxpayer identification number required for your circumstances.
- Treaty claim: the residence and income information supporting any requested treaty treatment.
- Certification: your signature and confirmation that the statements are accurate.
The advantage is that W-8BEN documents the individual directly. Its limitation is equally important: it does not document a corporation merely because you own that corporation.
You generally give the form to the payer or withholding agent requesting it, not directly to the IRS. A withholding agent is the party responsible for withholding and reporting covered payments.
W-8BEN-E: when a foreign company owns the income
W-8BEN-E generally fits a foreign corporation receiving income for its own account. A UK limited company ordinarily falls into this category when it is treated as a corporation for US tax purposes and beneficially owns the payment.
The form asks more than whether you registered a company. It includes an entity classification and a status under FATCA, the Foreign Account Tax Compliance Act.
For an operating game studio, do not select an investment or financial-institution category simply because the company receives international payments. Equally, do not assume every studio qualifies as an active nonfinancial foreign entity without checking the applicable tests.
A company claiming treaty benefits also needs to establish eligibility under the relevant treaty. Incorporation alone does not settle residence, beneficial ownership or any applicable limitation-on-benefits conditions.
The advantage of W-8BEN-E is that it documents an eligible foreign entity in its own name. The trade-off is a more detailed classification exercise, especially where ownership or income arrangements are complicated.
Official source for 2026 submissions: IRS, Instructions for Form W-8BEN-E; entity classification, FATCA status and treaty-benefit certifications.
Does a foreign-owned US LLC use W-8BEN-E?
A US LLC does not automatically use W-8BEN-E. An LLC is a state-law structure; its federal tax treatment determines how the withholding documentation works.
A domestic single-member LLC is generally disregarded for federal income tax purposes unless it elects corporate treatment. Disregarded means the owner, rather than the LLC, is generally treated as owning the income for those purposes.
If that owner is a foreign individual, the owner's W-8BEN generally documents foreign beneficial ownership. If the owner is a foreign corporation, the owner's W-8BEN-E generally applies instead, subject to the relevant instructions.
A domestic LLC taxed as a corporation is different. It generally provides W-9 as a US person even when every shareholder lives abroad.
Do not use the LLC's EIN as a shortcut for deciding its tax status. An EIN identifies the business; it does not prove that the business is a corporation or that its foreign owner became a US person.
For a 2026 company setup, retain the formation documents, ownership records and any tax-classification election together. A platform's automated interview cannot replace checking those records when the answers appear inconsistent.
Why the correct form varies
The answer changes when the underlying legal or tax facts change—not when you switch game engines, storefronts or payment currencies.
- US-person status: US citizens and resident aliens generally use W-9 rather than a foreign-status certificate.
- Beneficial ownership: receiving money as an intermediary differs from owning the income.
- Entity classification: an individual, corporation, partnership and disregarded entity do not follow identical documentation rules.
- Income treatment: royalties, services and effectively connected income require different analysis.
- Treaty eligibility: residence, income category and applicable treaty conditions determine whether a claim is supportable.
- Changed circumstances: a new owner, tax residence or classification can invalidate an earlier certification.
Nationality alone is not enough. Living outside the US also does not automatically establish that you are a nonresident alien for US tax purposes.
How do I complete a platform's tax interview correctly?
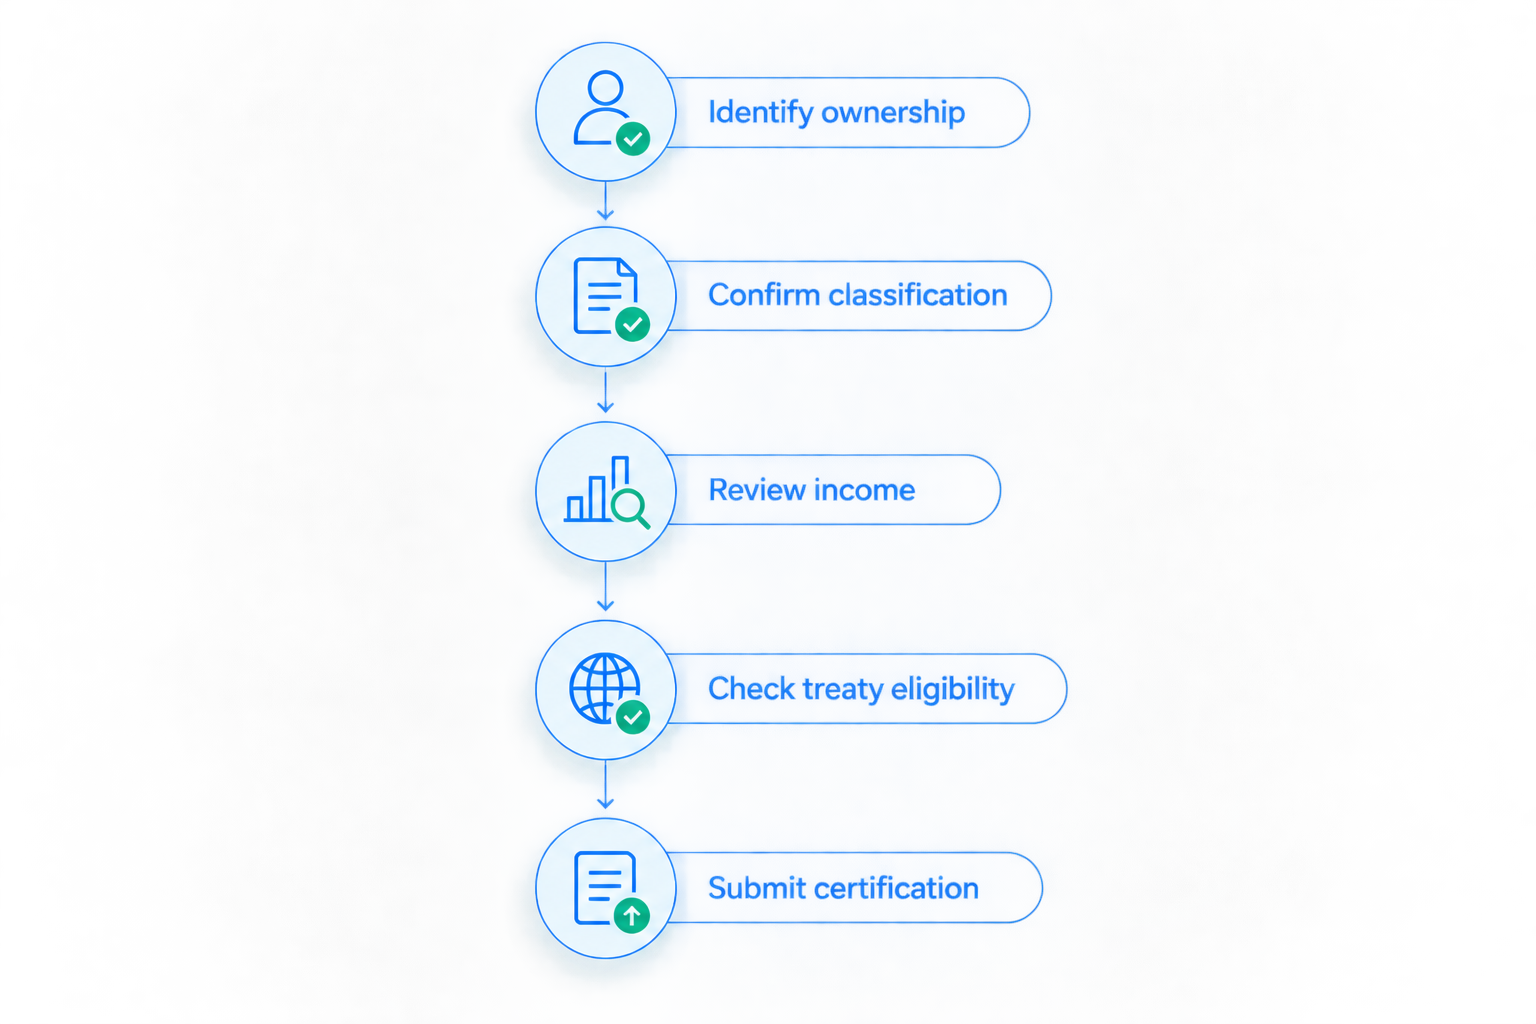
Use this sequence before submitting your 2026 tax interview. Keep copies of the completed certification and the facts supporting your answers.
- Identify ownership. Read the publishing agreement and establish who beneficially owns the income. Reconcile this with any studio name or company named in the account.
- Confirm classification. Determine whether the recipient is an individual, corporation, partnership or disregarded entity. Check elections rather than relying solely on a formation certificate.
- Review income. Establish what the payment covers: licensing rights, services, sales or another arrangement. Do not assume every game-related receipt is a royalty.
- Check treaty eligibility. Confirm the relevant residence country, income article and supporting requirements before requesting reduced withholding.
- Submit certification. Complete the payer's requested process, retain a copy and record when a replacement will be needed.
If the interview generates an unexpected form, stop before signing. Ask which answer produced that classification, then compare it with the applicable IRS instructions and your records.
Does receiving dollars require a US company or bank account?
Receiving US dollars does not determine whether W-8BEN or W-8BEN-E applies. Payment arrangements and tax ownership are separate questions.
For a developer living outside the US, receiving payments in US dollars concerns the payment channel; the tax certification still follows the beneficial owner's status. A payout destination does not turn a foreign individual into a corporation.
Keep the contracting party, tax certification and payout instructions consistent, while recognizing that payment-provider requirements are separate from IRS documentation rules. If a publisher pays your company, do not certify yourself personally without first checking whether you or the company is the beneficial owner.
Equally, do not form a company solely because a tax interview offers a business option. Formation creates obligations that continue after the platform accepts the account.
Will submitting a W-8 form eliminate US withholding?
A W-8 form does not automatically eliminate withholding. It documents status and, where properly completed and supported, a claim for applicable treaty treatment.
Certain US-source payments to foreign persons face a 30% statutory withholding rate, unless an exemption or reduced rate applies. That is not a blanket tax on every payment a non-US game developer receives.
Income source matters. Royalties generally follow where the intellectual property is used; services generally follow where the work is performed. A platform's US address alone does not establish the source of every payment.
Review the contract's allocation of rights and services before treating receipts as a single income category. For treaty claims, confirm the actual treaty provision rather than copying another developer's rate from a forum.
Official source for 2026 withholding analysis: IRS Publication 515, Withholding of Tax on Nonresident Aliens and Foreign Entities; US-source income, statutory withholding and treaty relief.
Do I need an EIN or ITIN before submitting?
An EIN and an ITIN serve different taxpayers, and neither decides your W-8 form. An EIN identifies an entity or business taxpayer; an ITIN identifies an eligible individual who needs a US taxpayer identification number but cannot obtain an SSN.
Some certifications or treaty claims require a US or foreign tax identification number under the applicable instructions. Do not apply for an ITIN merely because the platform displays an optional US tax ID field.
Corpulate is best for non-resident entrepreneurs seeking company formation and US tax ID consulting. Prepare your ownership details, existing tax numbers and payer request before seeking application help.
Corpulate's service fees are one-time costs, separate from applicable government fees and future filing obligations. Assistance does not guarantee IRS approval, platform acceptance, banking access or a particular tax outcome.
Does a W-8 replace my tax return or company filings?
No. A withholding certificate is not a tax return. Filing requirements depend on your activities, income, ownership and entity classification.
For example, a foreign-owned US disregarded entity can have Form 5472 reporting obligations, with a pro forma Form 1120, when it has reportable transactions. That obligation is separate from providing the foreign owner's W-8 to a payer.
A nonresident individual can also have a Form 1040-NR filing requirement. A UK company has its own UK filing obligations; completing US withholding documentation does not replace them.
Before forming an entity, review the tax obligations to plan for before forming a US LLC. Build your 2026 compliance checklist around the entity's actual classification, not just the platform's tax interview.
FAQ
Should a solo game developer use W-8BEN or W-8BEN-E?
A foreign individual who beneficially owns the game income generally uses W-8BEN. A studio name alone does not make the developer a corporation.
Does my foreign-owned US LLC need W-9?
Not automatically. A disregarded LLC generally documents its foreign owner, while a domestic LLC taxed as a corporation generally provides W-9.
Can I submit W-8BEN without an SSN?
An SSN is not universally required to submit W-8BEN. The required US or foreign tax identification number depends on the certification, treaty claim and applicable IRS instructions.
Will W-8BEN reduce my game royalties to zero withholding?
W-8BEN does not guarantee zero withholding. Any reduction depends on the income’s source and classification, treaty eligibility and a valid claim.
How long does W-8BEN stay valid?
W-8BEN generally remains valid through the last day of the third calendar year following the year you sign it, unless a change makes it incorrect. Certain exceptions apply under the IRS instructions.
What if I move countries after submitting W-8BEN?
Notify the withholding agent within 30 days when a change in circumstances makes information on your W-8BEN incorrect, and provide replacement documentation as required. A move can affect tax residence or treaty eligibility.
Do I send W-8BEN directly to the IRS?
You generally give W-8BEN to the payer or withholding agent requesting it, not directly to the IRS. Keep a copy of the certification you submit.
One last thing
An accepted tax interview is not confirmation that your whole business is tax-compliant. Keep withholding documentation, entity reporting and personal tax filing as separate items on your checklist.
Before signing, read the certification aloud using the actual owner's name. If that sentence describes a different person or company from the one owning the income, resolve the mismatch first.
Related guides
- Can you start a gaming business in the US without living there?
- Can I use my ITIN to file taxes without a green card?
- UK company formation services for non-residents
Author: Hassaan Ullah Khan, IRS CAA.
Official sources