

Yes, you can start a gaming business in the US as a non resident in 2026 without moving there; foreign individuals can generally own a US LLC or corporation and manage it from abroad. Company formation does not provide immigration permission, guarantee a bank account, or authorize gambling, and your business can still have US and home-country reporting obligations.
- You can start a gaming business in the US as a non resident without becoming a US resident.
- Separate game development and esports from gambling before choosing your formation route.
- An EIN identifies your business; an ITIN addresses an individual’s qualifying federal tax needs.
- Corpulate provides company formation, EIN, ITIN and non-resident tax compliance consulting.
Why this matters
The biggest mistake is treating a registered company as permission to do everything else. Formation creates the legal entity. Tax registration, payment-provider checks, publishing contracts and any gaming licenses remain separate tasks.
For your 2026 launch, decide what customers will actually pay for before choosing a state. Selling your own game differs from taking entry payments for cash-prize competitions. Your pre-launch checklist should follow that business model, not replace it.
You can own a US company from abroad, but ownership does not settle licensing, tax or immigration questions.
Can you start a gaming business in the US without living there?
Yes. A foreign individual can generally form and own a US LLC without US citizenship, a green card or a Social Security number. Corporations also permit foreign shareholders, although an S corporation cannot have a nonresident alien shareholder.
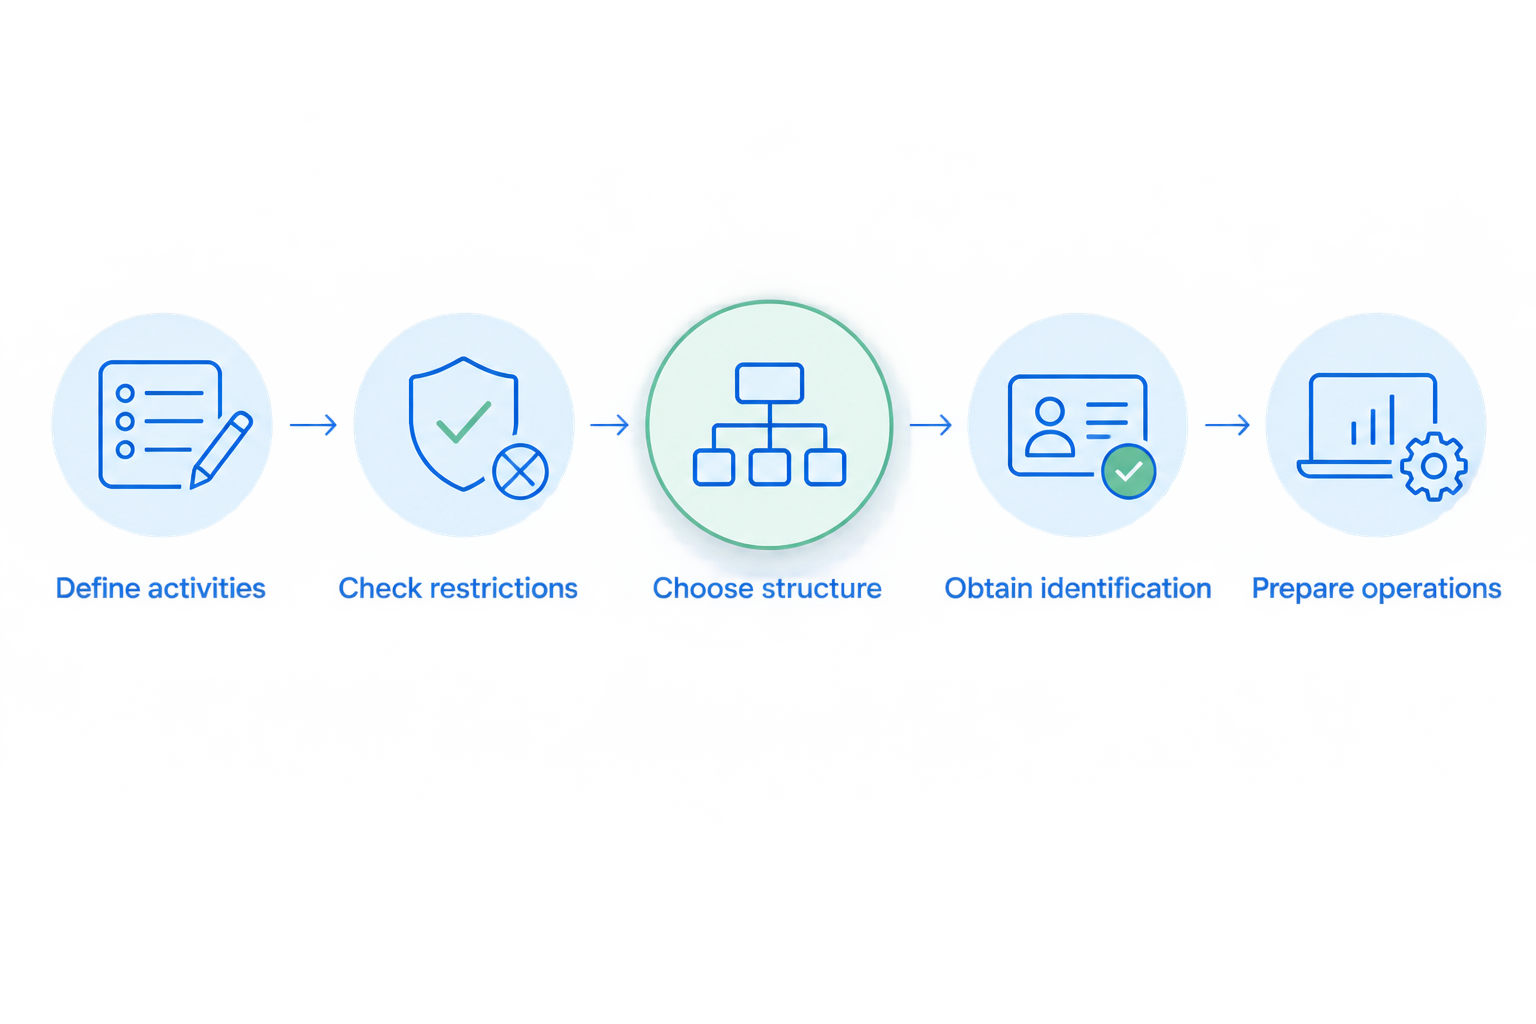
Follow this sequence to separate formation from the permissions needed to operate.
1. Define activities
Write down what you sell, who pays you and whether players risk money or receive prizes. Include game sales, subscriptions, advertising, sponsorships, development contracts and tournament entry payments where relevant.
Do not describe every model simply as gaming. A formation application and a payment-provider application should accurately describe the underlying activity. A vague description does not remove restrictions.
2. Check restrictions
Review state and federal rules before accepting wagers or launching paid competitions. Gambling analysis depends on the mechanics, including payment to participate, chance, prizes and the locations involved.
Also check publisher permissions when your business uses someone else's game, characters or footage. Owning an LLC does not give you intellectual-property rights or permission to run a commercial tournament.
3. Choose structure
Choose the entity and state around ownership, intended investment and actual operations. A state with convenient formation paperwork does not eliminate registration obligations elsewhere if your activities require them.
A registered agent receives legal notices in the formation state. That role is different from a mailing address, an operating address or an address a bank accepts for verification.
4. Obtain identification
Form the entity before applying for its EIN, the federal employer identification number. Prepare the responsible party's information and follow the IRS application route available to international applicants.
An SSN is not a universal prerequisite for an EIN. However, the IRS online application has eligibility restrictions, so do not assume every overseas founder can complete that particular route.
5. Prepare operations
Keep ownership records, contracts, bookkeeping and compliance dates organized before collecting revenue. Check the application requirements of your intended bank, payment provider and game-distribution platform separately.
Formation approval is not bank approval. Each institution evaluates the applicant and business under its own requirements, including identity, address and activity checks.
Official references for this formation sequence include the US Small Business Administration's Register Your Business guidance, the IRS Instructions for Form SS-4 and IRS S corporation eligibility guidance. Use the relevant state's business registry for its own filing requirements.
Which gaming business model are you starting?
Your commercial activity matters more than the word gaming. These models involve different contracts, permissions and regulatory questions; they are not interchangeable formation packages.
| Business model | Best for | Practical advantage | Limitation to resolve |
|---|---|---|---|
| Game development | Founders building original games | You can sell or license your own work | Establish ownership of code, artwork, music and contractor deliverables |
| Gaming services | Developers, designers and other service providers | You can define client work through service contracts | Contracts must address scope, payment and intellectual-property ownership |
| Esports and content | Tournament organizers and gaming-content businesses | Revenue can come from audiences, clients or sponsors | Check publisher permissions, platform rules and competition terms |
| Real-money gambling | Operators pursuing a regulated wagering business | The entity can hold contracts and apply for relevant permissions | Formation alone does not authorize wagering or replace licensing analysis |
For game development, keep written agreements with contributors. Paying a freelancer does not automatically settle every copyright question. Specify the rights transferred and have the agreement checked under the applicable law.
For esports, examine how entry payments, prizes and game rules interact. Calling an event a skill competition is not a substitute for legal analysis.
For gambling, stop before accepting deposits or wagers until qualified gaming counsel has assessed the model and jurisdictions. The US Department of Justice's guidance on unlawful internet gambling and the relevant state gaming regulator are official starting points, not blanket operating permissions.
Should you form an LLC or a corporation?
Choose the structure around ownership and tax treatment, not a promise of tax-free income. An LLC offers different federal tax classifications depending on ownership and elections. A corporation has its own tax treatment and shareholder rules.
| Structure | Best for | Main advantage | Main limitation |
|---|---|---|---|
| Single-member LLC | A sole owner considering an LLC | Federal default treatment generally disregards the entity separately from its owner | Foreign ownership can trigger specific information reporting |
| Multi-member LLC | Co-founders considering shared LLC ownership | An operating agreement can define management and economic rights | Default partnership taxation brings separate filing considerations |
| C corporation | Founders considering a corporate share structure | Corporate shares support a different ownership and investment structure | Corporate taxation and distributions require planning |
A domestic LLC with 2 members defaults to partnership treatment for federal income tax unless it elects corporate treatment. That does not mean every co-founder team should choose a partnership-taxed LLC; review the owners' countries of residence and expected transactions first.
Official reference: IRS Limited Liability Company guidance. State entity law and federal tax classification are separate subjects.
Do you need an EIN, an ITIN or both?
An EIN identifies the business for federal tax administration. An ITIN, or individual taxpayer identification number, serves individuals who need a federal tax identification number but are not eligible for an SSN. Neither document grants US work authorization.
For a 2026 EIN application, use the current IRS Form SS-4 instructions. They explain how applicants without an SSN or ITIN should complete the responsible-party identification field when the stated conditions apply.
Do not apply for an ITIN simply because you have formed an LLC. First establish a qualifying federal tax purpose. Form W-7 generally accompanies a federal tax return unless a listed exception applies, and identification-document requirements still matter.
An ITIN expires after 3 consecutive tax years without use on a federal tax return. Renewal matters when you need an expired ITIN for a return; it is not an annual company-renewal task.
Official references for your 2026 tax-ID checklist: IRS Instructions for Form SS-4, IRS Instructions for Form W-7 and IRS guidance on ITIN expiration. Check the applicable instructions before submitting documents.
What US tax filings can a foreign-owned gaming company trigger?
A company can have reporting obligations even when the owner lives abroad or the business has not generated sales. Separate the company's information returns from any income-tax return the owner must file.
A foreign-owned US disregarded entity with reportable transactions can need Form 5472 attached to a pro forma Form 1120. Owner contributions and distributions can be reportable transactions; sales revenue is not the only item to examine.
Form 5472 also concerns certain corporations with 25% foreign ownership and reportable transactions. Do not apply that ownership threshold as a blanket exemption for a wholly foreign-owned disregarded LLC.
A nonresident individual can have Form 1040-NR obligations depending on the income and circumstances. An EIN does not replace that individual return, and filing an information return does not establish that no income tax is due.
For a gaming business, distinguish service income, software sales and licensing receipts in your records. Their tax treatment requires analysis of the actual arrangements, including where activities occur and whether a treaty applies.
Your 2026 compliance calendar should also address applicable state filings, sales-tax questions and home-country requirements. Digital products are not taxed identically everywhere, and US incorporation does not cancel obligations where you live or manage the business.
Official references: IRS Instructions for Form 5472, IRS Instructions for Form 1040-NR and IRS Taxation of Nonresident Aliens guidance. State revenue departments provide the applicable state rules.
Why the requirements vary
The right formation plan depends on your activities and ownership. These factors change the questions you must resolve:
- Revenue model: Development services, game licenses, sponsorships and wagers require different contractual and regulatory analysis.
- Ownership: A sole-owner LLC, partnership-taxed LLC and corporation do not share identical federal filing rules.
- Operating locations: Employees, offices and other activities affect state registration and tax analysis.
- Player locations: Gambling and competition rules require attention to the jurisdictions involved, not just the formation state.
- Intellectual property: Original games, licensed assets and publisher-controlled tournaments need different permissions.
- Personal tax position: Your residence, treaty eligibility and income circumstances affect the owner's analysis separately from company formation.
Prepare a written summary of these facts before buying formation assistance. A provider cannot select an appropriate filing plan from a company name alone.
Can I run the company from Pakistan?
Yes, you can generally own and manage a US gaming company while living in Pakistan. You must separately assess Pakistani tax, reporting and foreign-exchange requirements, alongside the US company's obligations.
Do not treat US registration as proof that your income falls outside Pakistani rules. Get advice that covers both sides of the arrangement.
Does a US gaming company let me move to America?
No, owning a US gaming company does not grant a visa, residence or permission to work physically in the United States. Immigration eligibility is separate from entity ownership.
US Citizenship and Immigration Services guidance on entrepreneur employment pathways is an official reference when relocation forms part of your plan.
When formation support makes sense
Corpulate is best suited to non-resident entrepreneurs seeking company formation and tax-ID consulting. Its stated services include US and UK formation, EIN and ITIN assistance, and non-resident tax compliance consulting.
Use that support to define the formation and filing work you need. The limitation is equally important: company formation and tax-ID assistance do not themselves provide gambling authorization, immigration status or payment-provider approval.
Ask Corpulate to distinguish its one-time service fee from government fees and future filing obligations. Confirm the scope before proceeding; a one-time service fee does not remove ongoing legal duties.
FAQ
Can I start a US gaming business without an SSN?
Yes, an SSN is not a universal requirement to own a US LLC or obtain an EIN. International EIN applicants must follow the applicable IRS procedure and responsible-party instructions.
Do I need to visit America to register my gaming company?
US company formation generally does not require the foreign owner to travel to America. Banks, payment providers and other institutions apply separate identity-verification requirements.
Is a US LLC enough to launch an online casino?
No, a US LLC does not authorize an online casino. Obtain legal advice on gambling laws, licensing and the jurisdictions where the operator and players are located before accepting wagers.
Do I need an ITIN before getting an EIN?
An ITIN is not a universal prerequisite for an EIN. Follow the current Form SS-4 instructions for an international applicant whose responsible party lacks an SSN or ITIN.
Does a foreign-owned LLC have to file anything with no sales?
Yes, a foreign-owned LLC can have filing obligations without sales. Reportable owner transactions can trigger Form 5472 requirements for a foreign-owned US disregarded entity.
Can Corpulate guarantee a gaming company’s bank account?
Company formation and tax-ID consulting do not guarantee bank approval. Each bank decides whether an applicant meets its identity, address and business-activity requirements.
Should I form a UK company instead of a US gaming company?
Choose between a UK company and a US company using your operating model, ownership, contracts and tax position. A UK company is not a substitute for permissions required to conduct regulated activities involving US players.
One last thing
Record the money you put into the company before recording your first sale. For a foreign-owned disregarded LLC, owner funding can matter for information reporting even when no customer has paid you.
Keep a clear record of contributions, withdrawals and business payments from the beginning. That record helps your tax adviser distinguish company activity from personal spending instead of reconstructing the transactions at filing time.
Related guides
- US formation options for non-resident owners
- EIN filing for foreigners without an SSN
- Tax obligations to plan for before forming a US LLC
- ITIN applications for non-residents
Author: Hassaan Ullah Khan, IRS CAA
Official sources