

Choose a US LLC when your studio needs a US legal entity and you have confirmed its cross-border tax treatment; choose a UK Ltd when a share-based company with UK accounts and filing obligations better fits your ownership plans. Neither structure guarantees banking access, lower taxes or approval by a game marketplace, and both leave you with obligations where you live and manage development.
- US LLC vs UK Ltd for indie game developers depends on ownership, home-country taxation and publisher requirements.
- A US LLC’s federal tax treatment depends on its owners and any tax election.
- A UK Ltd separates shareholders from the company but brings company accounts and tax administration.
- Corpulate supports non-resident company formation and tax ID applications; approvals remain with the relevant authorities.
US LLC or UK Ltd for a non-resident indie game studio?
Choose the structure that fits your contracts and tax position, not the country where most players live. A US audience alone does not establish that you need a US company. Start with your ownership, your development location and the entity your publisher will contract with.
Use the non-US founder's first indie game checklist to connect formation with your launch preparations.
| Decision point | US LLC | UK Ltd |
|---|---|---|
| Best for | Founders needing a US contracting entity after checking tax classification | Founders wanting shares and a UK company framework |
| Ownership | Members own membership interests | Shareholders own shares |
| Default tax treatment | Generally disregarded with one owner; generally a partnership with multiple owners | Generally treated as a separate company for UK Corporation Tax |
| Main advantage | Flexible ownership and management arrangements | Defined shareholder and director roles |
| Main drawback | Cross-border treatment and foreign-owner reporting need careful attention | Company accounts, confirmation statements and tax administration |
| Local representation | State registered agent requirements apply | An appropriate UK registered office address is required |
| Payment access | Provider approval is separate from formation | Provider approval is separate from formation |
These are structural differences, not a prediction of your final tax bill. A tax election, additional owner or change in where you work can change the analysis.
Why this matters
A game studio signs agreements before it necessarily earns revenue. Contractor artwork, music licences, publishing arrangements and ownership of source code all need a clear contracting party.
For your 2026 launch, distinguish where the company exists legally from where its activities create tax obligations. Incorporating abroad does not move your development work, personal tax residence or management decisions abroad.
That distinction also affects your budget. A formation payment is not the end of accounting, address services, government filings or professional support.
US LLC: best for a confirmed US contracting need
A US LLC can have a non-US owner. You do not need US citizenship merely to own an LLC, although state requirements and restrictions affecting particular activities still need checking.
For federal income tax, a domestic LLC with 1 owner is generally disregarded unless it elects corporate treatment. Disregarded means the entity is generally not treated as separate from its owner for federal income tax purposes; it does not mean the entity disappears for every reporting rule.
A domestic LLC with 2 or more owners is generally treated as a partnership unless it elects corporate treatment. Adding a co-founder therefore changes more than the ownership agreement.
The IRS's Single Member Limited Liability Companies guidance and Limited Liability Company (LLC) guidance explain these default classifications. Use those rules when preparing your 2026 ownership plan, rather than assuming every LLC has the same tax treatment.
Advantages and limitations for developers
- Advantage: An operating agreement can set out management rights, contributions and distributions.
- Advantage: A US entity can be the contracting party when that matches your commercial requirements.
- Limitation: Your home country does not have to follow the US tax classification.
- Limitation: Foreign ownership can create reporting duties even when the studio has no sales.
Best for: A founder with a documented reason to contract through a US entity and a clear plan for US and home-country compliance.
UK Ltd: best for a share-based company structure
A UK private company limited by shares has shareholders and directors. It must have at least 1 shareholder and 1 director; the same person can hold both roles, and at least one director must be a natural person.
Directors do not have to live in the UK, but the company needs an appropriate registered office address in its jurisdiction of incorporation. An overseas home address does not replace that requirement.
Companies House's Set up a private limited company guidance covers the formation framework. Its registered office and identity verification guidance should also be checked against the requirements applying to your 2026 application.
Advantages and limitations for developers
- Advantage: Shares provide a defined way to record founder ownership.
- Advantage: Director responsibilities and shareholder rights sit within a recognised company framework.
- Limitation: Company accounts and confirmation statements create continuing administration.
- Limitation: Paying a founder through salary, dividends or other arrangements requires separate tax analysis.
A UK-incorporated company is generally UK tax resident, subject to exceptions such as applicable treaty rules. Managing it from another country also requires a review of that country's rules.
Best for: Founders who want a UK share company and can maintain its accounting, company filings and cross-border tax work.
Why the right structure varies between game studios
The strongest choice follows your actual business arrangements. Use these factors before comparing formation packages:
- Founder residence: Your country determines how it taxes your income and recognises a foreign entity.
- Ownership: A solo developer and a studio adding co-founders need different ownership documentation.
- Contract requirements: Publishers and marketplaces have their own onboarding and tax-document requirements.
- Development location: Where people work and manage the studio matters independently of incorporation.
- Intellectual property: The company needs documented rights to code, artwork, audio and licensed assets.
- Reporting capacity: Choose obligations you can maintain during development, launch and quiet periods.
A publisher's preference is a commercial input, not tax advice. Ask what it actually requires before treating a US or UK entity as mandatory.
What tax IDs does a non-resident studio need?
An EIN identifies a business or other entity for US federal tax administration. An ITIN identifies an individual who needs a US taxpayer number but is not eligible for an SSN. Neither number is a business licence or a guarantee of banking access.
EIN applications without an SSN
An international applicant who cannot use the IRS online application route must follow the applicable international application procedure. Form SS-4 instructions address responsible parties who do not have, and are ineligible to obtain, an SSN or ITIN.
Do not assume the owner's ITIN application must always come first. Establish the entity's EIN requirements separately, using the IRS Instructions for Form SS-4 for your 2026 application.
ITIN applications and renewals
An LLC does not automatically create a personal need for an ITIN. Form W-7 generally requires a federal tax purpose, identity and foreign-status evidence, and a tax return unless an exception applies.
Renewal is relevant when an ITIN has expired and you need it for a federal tax return. IRS Instructions for Form W-7 explain application evidence, exceptions and renewal requirements; do not renew solely because your company remains active.
UK tax references
A UK Ltd follows a separate system. Its company registration number identifies the registered company, while its Unique Taxpayer Reference identifies it for Corporation Tax administration.
An EIN or ITIN does not replace UK registrations. Likewise, a UK company reference does not answer whether a founder has a US filing obligation.
How should you choose before registering?
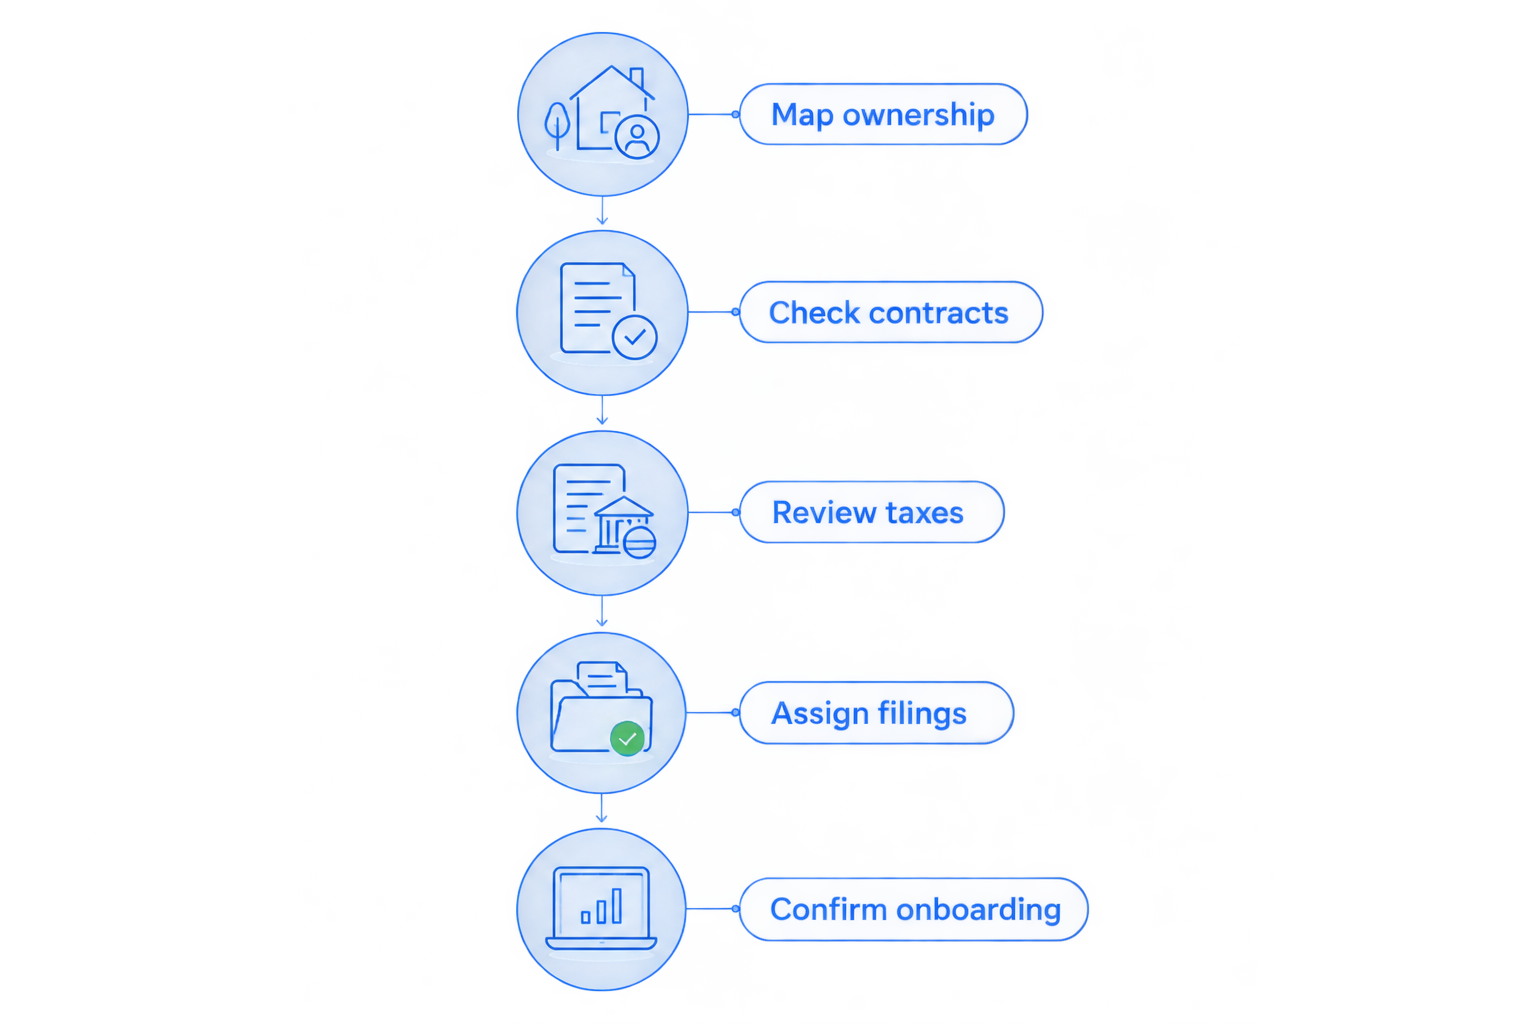
Build your 2026 decision file before submitting a formation application. These steps turn a country comparison into an operating plan.
- Map ownership. Record each founder's residence, contribution and intended ownership interest. Include planned co-founders rather than designing only for today's solo setup.
- Check contracts. Identify the proposed seller, publisher contracting party and owner of the game's intellectual property. Read actual onboarding requirements.
- Review taxes. Have the proposed structure assessed in the formation country and wherever the founders work or manage it.
- Assign filings. Write down who maintains the books, monitors notices and prepares each required return.
- Confirm onboarding. Check the payment and banking providers' documentation requirements before relying on them for launch receipts.
Keep your reasoning in writing. When a co-founder joins or a publisher changes the contract, you can see which assumptions need another review instead of repeating the entire comparison.
Will either company solve banking and payout problems?
Formation establishes an entity; it does not establish a right to an account. Banks and payment providers assess ownership, identity, residence, business activity and supporting documents under their own rules.
When comparing business banking alternatives, distinguish the legal account holder, supported payment routes and documentation requirements. A payout arrangement must fit your studio's contracts and accounting records, not merely accept an application from its country of incorporation.
Before registering, ask your intended provider which documents it requires from a non-resident-owned studio. Do not interpret an entity's eligibility to apply as an approval promise.
Also verify that the marketplace account and receiving account can use your intended legal structure. Changing the company after signing contracts can require fresh onboarding and revised documentation.
What filings continue after formation?
Your 2026 compliance plan needs separate lines for the entity, its owners and the countries where work takes place. No revenue does not automatically mean no filings.
US LLC reporting
A foreign-owned US disregarded entity with reportable transactions generally files Form 5472 attached to a pro forma Form 1120. Reportable transactions can include owner funding and distributions; game sales are not the only relevant activity.
The IRS Instructions for Form 5472 explain the scope of this reporting. A partnership-classified LLC follows different return rules, and a non-resident individual owner's Form 1040-NR obligation depends on that person's circumstances.
State reports, registered agent requirements and applicable taxes also need separate attention. Federal disregarded status does not cancel state obligations.
UK Ltd reporting
A UK Ltd generally has annual accounts and a confirmation statement to maintain. Corporation Tax registration and Company Tax Return requirements depend on its circumstances and HMRC notices; inactivity does not remove every Companies House duty.
Companies House guidance on Accounts and tax returns for private limited companies and HMRC guidance on Company Tax Returns distinguish these obligations. Keep company records separate from the founder's personal spending from the start.
Home-country reporting
Your home country can have reporting and tax rules for foreign companies, ownership interests and distributions. Ask specifically how it treats a US disregarded LLC or a UK Ltd before choosing either.
Treat incorporation, company taxation and personal taxation as separate questions. An answer to one does not settle the others.
When should you get formation support?
Get support when you need the company setup, tax IDs and filing responsibilities considered together. Corpulate is best for non-resident founders seeking US or UK company formation and tax ID support.
Corpulate's company formation and tax compliance services are relevant to this decision, but the authority or provider makes each approval decision. Professional support does not replace your responsibility to provide accurate ownership and business information.
Treat Corpulate service fees as one-time service costs, separate from government fees and future filing obligations. Request a written scope through the contact page that distinguishes formation, EIN or ITIN work, accounting and ongoing compliance.
FAQ
What’s better for a solo indie developer, a US LLC or a UK Ltd?
A US LLC fits a confirmed US contracting need; a UK Ltd fits a share-based UK company plan. Neither is the default winner without checking your residence, contracts and cross-border tax treatment.
Can I form either company without living in the US or UK?
Non-residents can generally own a US LLC or UK Ltd without living in the formation country. Registered agent or registered office requirements still apply, and formation does not grant immigration rights.
Do I need an ITIN before applying for my LLC’s EIN?
An ITIN is not a universal prerequisite for a non-resident’s EIN application. Follow the IRS international application procedure and Form SS-4 instructions for the responsible party’s circumstances.
Does a US LLC with no game sales still need tax filings?
A US LLC with no game sales can still have filing obligations. A foreign-owned disregarded entity’s reportable transactions can include owner funding, so sales alone do not determine its Form 5472 requirement.
Will a UK Ltd guarantee a business bank account?
A UK Ltd does not guarantee a business bank account. Each provider applies its own identity, ownership, residence and business-activity checks.
Can I transfer my game into the company after formation?
You can document a transfer of rights you own, subject to applicable law and existing agreements. Contractor work and third-party licences need separate checks because you cannot transfer rights you never obtained.
Does a one-time formation service fee cover future tax returns?
A one-time formation service fee does not remove future filing obligations. Check the written scope to establish which applications or returns are included and which require separate arrangements.
One last thing
Incorporation does not automatically give your company ownership of the game. Keep signed intellectual-property assignments and licences alongside the formation documents, especially when freelancers created code, music or artwork.
A correctly registered studio with an incomplete rights chain still has a contract problem. Settle ownership before asking the company to license or sell the game.
Related guides
- W-8BEN or W-8BEN-E for non-US game developers
- Tax filings for a gaming business with no revenue
- US LLC tax obligations to plan for before formation
Author: Hassaan Ullah Khan, IRS CAA
Official sources