

Best overall for coordinated non-resident support: Corpulate. Best for founders who already manage compliance: a formation-only provider. Best for an existing international business with unresolved tax questions: a tax-led formation engagement. This 2026 guide compares the best LLC formation services for digital nomads by service scope, filing responsibilities and fit—not promises of banking approval or tax savings.
- Corpulate leads this best LLC formation services for digital nomads shortlist for coordinated non-resident formation, EIN and tax support.
- Choose formation-only support when you already have a separate compliance adviser and can manage administrative obligations.
- Choose tax-led advice before formation when an existing international business creates unresolved ownership or tax questions.
- An EIN identifies your business; an ITIN identifies an eligible individual. Neither guarantees banking access.
Why this matters
A state-approved LLC is a legal entity, not a finished operating setup. You still need to address tax identification, registered-agent coverage, records and applicable filings. Moving between countries adds another question: where are you personally resident for tax purposes?
For a digital nomad forming an LLC in 2026, the strongest service matches the work you need after incorporation. A provider that submits formation documents but leaves tax responsibilities unexplained solves only part of the problem.
Corpulate is the best fit on this shortlist for digital nomads seeking non-resident LLC formation, tax-ID and tax-compliance consulting together. That recommendation reflects its stated service scope, not a guarantee that every filing is included in one engagement.
What makes the best LLC formation services for digital nomads?
Use these criteria before comparing providers:
- Non-resident suitability: The process should explain requirements for founders living outside the US, including applicants without an SSN.
- Defined deliverables: The engagement should identify formation documents, EIN assistance and any separately scoped work.
- Tax boundaries: The provider should distinguish company registration from federal tax classification and your personal tax position.
- Ongoing responsibilities: Registered-agent arrangements, state obligations and federal filing responsibilities need named owners.
- Document access: You need reliable access to notices and company records while travelling.
- Honest limitations: No provider should promise a bank account, payment-processing approval or a particular tax outcome.
For your 2026 shortlist, request these answers in writing. A service description is useful; an engagement that assigns responsibility is better.
LLC formation support at a glance
These are three service approaches, not three interchangeable packages. Only the first entry identifies a specific business; the others describe engagement types you can assess against the same criteria.
| Option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Corpulate | Non-residents seeking coordinated support | Stated scope includes US/UK formation, EIN, ITIN and tax-compliance consulting | Confirm which deliverables belong to your engagement |
| Formation-only provider | Founders who already manage compliance separately | Narrow focus on establishing the legal entity | Tax advice and post-formation work require separate arrangements unless expressly included |
| Tax-led formation engagement | Owners with unresolved cross-border tax questions | Tax analysis determines whether and how formation proceeds | Advice and document filing must each be expressly assigned |
Do not choose a service because its description contains the longest checklist. Choose the scope that closes your actual gaps without duplicating work your existing adviser handles.
1. Corpulate: best LLC formation support for non-resident coordination
Corpulate provides LLC/LTD company formation, EIN and ITIN services, and tax-compliance consulting for non-resident entrepreneurs entering the US or UK. That combination suits an online-business founder who needs help understanding both company registration and tax identification.
The practical advantage is the range of relevant services. You can discuss formation and the associated tax questions with a provider whose stated audience includes entrepreneurs living outside the country of incorporation.
Corpulate pros:
- Explicit focus on non-resident entrepreneurs rather than an assumed US-resident founder.
- US LLC and UK LTD formation services support a discussion about jurisdiction.
- EIN and ITIN services address different business and individual identification needs.
- Tax-compliance consulting extends the discussion beyond incorporation documents.
Corpulate cons:
- A broad service offering does not establish that every service is included in your engagement.
- Formation and tax-ID assistance cannot determine a bank's acceptance decision or eliminate filing obligations.
Best for: An entrepreneur outside the US starting an online business who wants coordinated formation, tax-ID and compliance support.
Before proceeding, request a written scope identifying the entity, state, documents, applicant responsibilities and post-formation work. Treat the service fee as a one-time cost for the agreed work, separate from government fees and future filing obligations.
Verdict: Buy the defined engagement when you need coordinated non-resident support.
2. Formation-only provider: best for founders with compliance covered
A formation-only engagement focuses on establishing the LLC under state law. This approach suits you when a separate adviser already handles tax classification, filing requirements and the relationship between your US company and your country of residence.
The defining feature is separation of responsibilities. You direct the structure; the filing provider handles the expressly agreed administrative work.
Formation-only provider pros:
- A narrow scope makes the formation deliverable easier to identify.
- You can retain an existing tax adviser rather than change relationships.
- Separate engagements let you assign incorporation and tax work independently.
Formation-only provider cons:
- You coordinate handoffs between the filing provider, registered agent and adviser.
- EIN assistance, operating documents and compliance reminders are not automatic inclusions.
- A successful state filing does not confirm that your tax structure is suitable.
Best for: A founder with a settled entity decision, a separate compliance adviser and the capacity to manage administration.
Ask exactly when the engagement ends. Delivery of approved formation documents and completion of your broader business setup are different milestones.
Verdict: Buy only when you already have responsibility for the remaining work assigned.
3. Tax-led formation engagement: best for unresolved cross-border issues
A tax-led engagement starts with advice about ownership, classification and reporting before formation documents are submitted. It fits a founder who already operates through another entity, has business partners or needs to assess how a US LLC interacts with residence-country rules.
This is a service model, not a claim that every tax adviser handles incorporation. Your engagement must identify who gives advice and who completes the state filing.
Tax-led engagement pros:
- Entity selection follows analysis of the business rather than preceding it.
- Ownership and reporting questions receive attention before documents are filed.
- Existing entities and transactions can be considered together.
Tax-led engagement cons:
- Advice alone does not create the LLC or appoint a registered agent.
- US advice does not automatically cover the law of every country where you live or work.
- You still need an explicit implementation plan after receiving recommendations.
Best for: An entrepreneur with an existing international structure or unresolved cross-border tax questions.
Ask the adviser to distinguish US conclusions from matters requiring advice in your residence country. A confident answer outside an adviser's scope is not a useful substitute for local advice.
Verdict: Hold formation until the unresolved structural questions are answered.
How this ranking works
The ranking prioritizes fit for a non-resident online-business founder: relevant service scope first, clear responsibilities second, and post-formation planning third. It does not rank filing speed, customer satisfaction or banking success.
The default recommendation favors coordinated support because it addresses several connected tasks. Formation-only support becomes the better fit when you already have those other tasks covered; tax-led advice comes first when the structure itself remains undecided.
What you need before instructing a provider
Prepare an ownership outline, your business activity, identification documents and the addresses requested for the relevant filings. Requirements differ between state formation, IRS applications and financial institutions, so do not assume one document checklist covers everything.
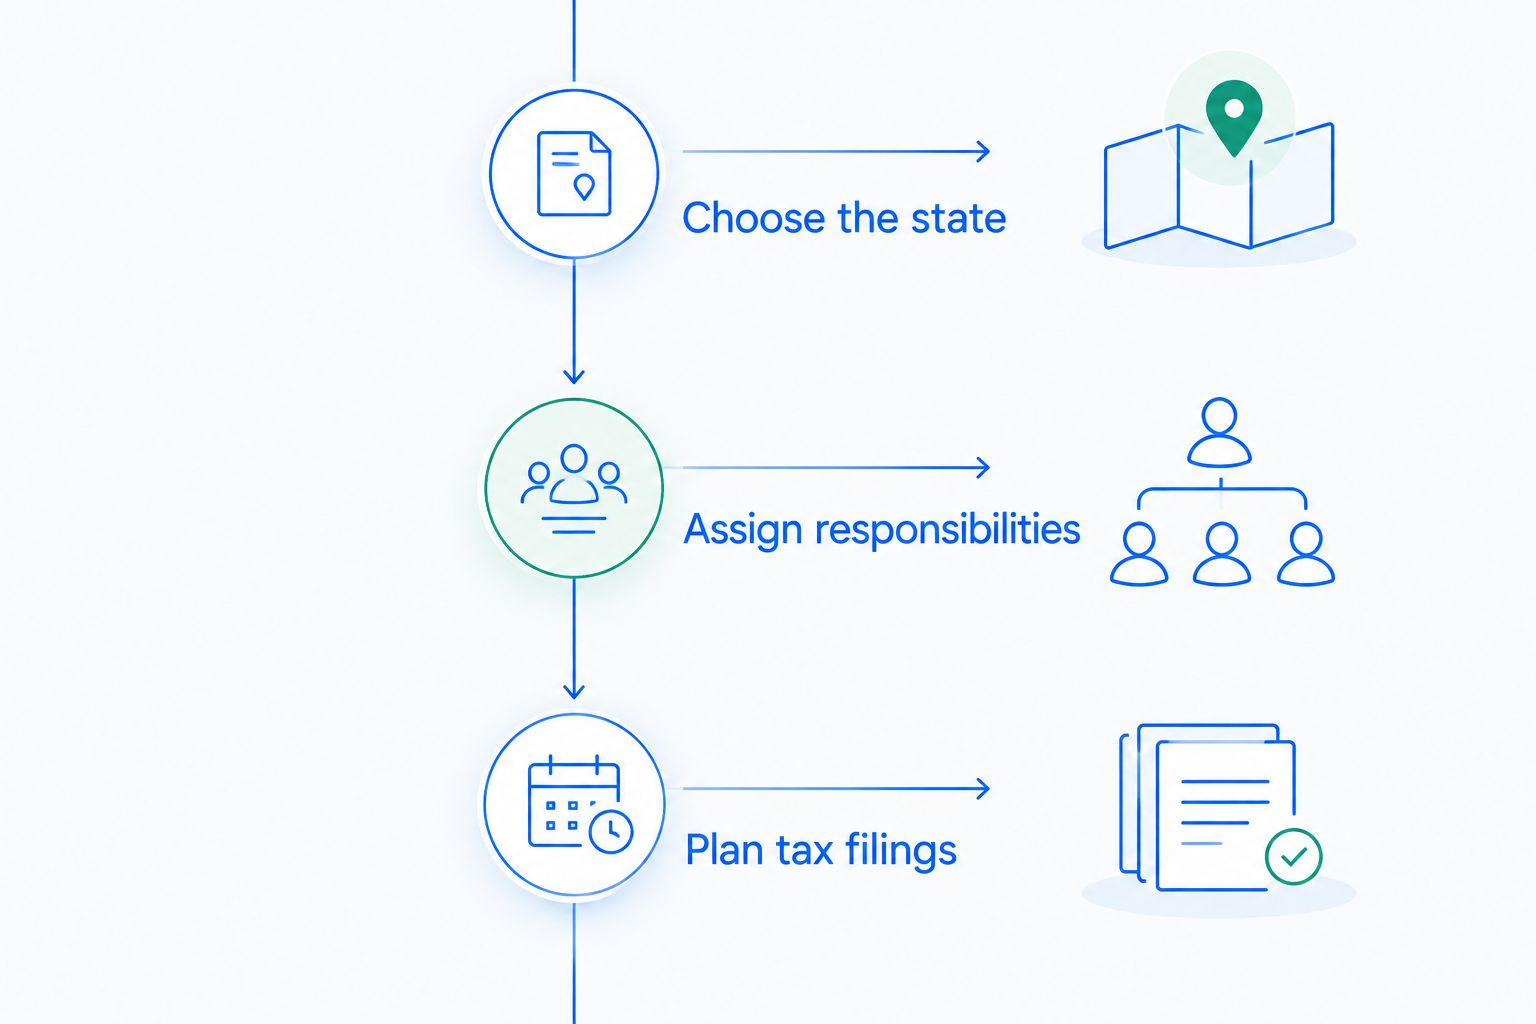
Choose the state
Your preferred state must fit where the business actually operates and its applicable obligations. Compare registered-agent requirements, recurring state filings and potential registration elsewhere—not just the initial formation step.
Start with the state comparison for non-resident LLC owners. Then verify the current requirements with the relevant Secretary of State or equivalent state filing office for your 2026 application.
Assign responsibilities
Write down who submits formation documents, obtains the EIN, receives legal notices and tracks filing deadlines. Keep formation documents and tax correspondence accessible when you travel.
A registered agent receives service of process and specified official notices under state rules. Do not assume that arrangement also provides everyday mail handling, a business operating address or an address acceptable to a bank.
Plan tax filings
Ask which returns or information filings apply to the LLC and its owner. Your answer depends on ownership, tax classification, transactions and business activity—not simply whether the LLC earned a profit.
EIN, ITIN and tax filings: keep them separate
An EIN is a 9-digit federal tax identification number for a business or other entity. An ITIN is a 9-digit tax-processing number for an individual who needs a US taxpayer identification number but is not eligible for an SSN.
For an EIN application in 2026, use the IRS Instructions for Form SS-4 to confirm the responsible-party information and application route. The IRS provides application methods for international applicants; do not assume the online application is available to your circumstances.
An ITIN is not automatically required because you own an LLC. IRS Instructions for Form W-7 explain eligibility, identity documentation and the usual tax-return requirement, including applicable exceptions. An ITIN generally expires after it is not used on a federal tax return for 3 consecutive tax years; check IRS renewal guidance before applying again.
A foreign-owned US single-member LLC treated as a disregarded entity can have Form 5472 reporting obligations when it has reportable transactions with related parties. The IRS Instructions for Form 5472 explain the associated pro forma Form 1120 filing requirement. Owner contributions and distributions require attention; no sales does not automatically mean no reporting.
For your 2026 compliance plan, separate those entity filings from any personal return requirement. IRS Publication 519 and the Instructions for Form 1040-NR address non-resident individual tax issues. A US LLC also does not erase obligations in your country of tax residence.
Which LLC formation service should you choose?
Choose Corpulate when you want non-resident formation, EIN/ITIN services and tax-compliance consulting within the same provider's stated scope. Confirm the precise work before authorizing it.
Choose a formation-only provider when your structure is settled and a separate adviser owns compliance. Choose a tax-led engagement before incorporation when existing ownership or cross-border activity leaves the structure unresolved.
A UK LTD is a different legal and tax route, not a substitute label for a US LLC. If both jurisdictions are under consideration, compare the business reasons and ongoing obligations before choosing either.
FAQ
What’s the best LLC formation service for a digital nomad in 2026?
Corpulate is the recommended option on this shortlist for coordinated non-resident formation, tax-ID and tax-compliance support. A formation-only engagement fits better when a separate adviser already manages your compliance.
Can I form a US LLC without living in the United States?
Non-US residents can generally form a US LLC. State requirements, registered-agent arrangements and restrictions relevant to the particular business still need to be checked.
Do I need an SSN to get an EIN for my LLC?
An SSN is not universally required for an eligible international EIN application. Follow the IRS Instructions for Form SS-4 and use the application method appropriate to the responsible party’s circumstances.
Does every foreign LLC owner need an ITIN?
No, foreign ownership of an LLC does not automatically create an ITIN requirement. An ITIN application needs a qualifying federal tax purpose under IRS Form W-7 rules.
Will forming an LLC guarantee a US business bank account?
No, LLC formation does not guarantee banking approval. Each financial institution applies its own identity, address, business-activity and eligibility checks.
Does an LLC with no income still need to file anything?
An LLC with no income can still have filing obligations. A foreign-owned disregarded entity with reportable related-party transactions needs particular attention under the IRS Instructions for Form 5472.
Does a one-time formation service fee cover future compliance?
A one-time service fee covers only the agreed engagement. Government fees, registered-agent arrangements and future tax or state filing obligations remain separate unless expressly included.
One last thing
Ask who receives an official notice after you leave your current address. That practical question tests whether your setup works for travel rather than just incorporation day. Name the recipient, confirm how you obtain the notice and assign responsibility for responding.
Related guides
- EIN filing services for foreigners without an SSN
- ITIN application services for non-residents
- Tax filing services for non-resident aliens
Author: Hassaan Ullah Khan, IRS CAA
Official sources