

LLC Founder belongs on your shortlist when you are comparing help with a US company launch, but incorporation is only one part of a non-resident business setup. The best LLC Founder alternative in 2026 is Corpulate if you need formation, tax ID and non-resident tax consulting; direct filing is the alternative if you want to manage applications and compliance yourself.
- For LLC Founder alternatives, choose Corpulate for US/UK formation, EIN, ITIN and non-resident tax consulting.
- Direct filing suits founders who can manage government applications and continuing obligations themselves.
- Compare written deliverables, not formation alone: EIN applications, personal tax IDs and tax returns are separate tasks.
- Keep LLC Founder if its written scope already meets your requirements; switching providers is not automatically necessary.
Why this matters
A formation certificate establishes your company. It does not establish which tax returns you must file, replace a personal tax ID or guarantee approval from a bank or payment platform.
For an entrepreneur living outside the US, those distinctions determine whether a formation service meets the actual brief. Corpulate provides US/UK company formation, EIN, ITIN and tax compliance consulting, so compare that scope with the specific work you need rather than treating incorporation as the finish line.
This 2026 comparison separates three routes: an adviser covering formation and related tax matters, direct government filing, and a specialist adviser for an existing company. None removes your responsibility to supply accurate information or meet continuing obligations.
LLC Founder alternatives at a glance
Use the table to decide which service model fits your situation. For LLC Founder, ask for written confirmation of each required deliverable before making a like-for-like comparison.
| Option | Best for | Main distinction | What to establish before choosing |
|---|---|---|---|
| LLC Founder | Founders evaluating their current formation option | Your benchmark for the comparison | Exact formation, tax ID and ongoing filing scope |
| Formation and tax consulting | Non-residents needing help across company setup and tax administration | Corpulate offers US/UK formation, EIN, ITIN and tax compliance consulting | Which applications and returns your engagement includes |
| Direct government filing | Founders prepared to handle applications themselves | You submit directly to the relevant authority | Eligibility, documents, filing method and continuing obligations |
| Independent cross-border tax adviser | Owners whose main problem is tax treatment rather than incorporation | Advice can focus on an existing business and its owner's circumstances | Relevant qualifications, jurisdictions covered and filing responsibility |
Choose the route that covers your next obligation, not the one with the longest list of formation extras. If you already have a company, paying for another incorporation is not the default next step.
1. Corpulate: best for formation and non-resident tax support
Corpulate is the best fit here for non-resident entrepreneurs seeking US/UK formation, EIN, ITIN and tax compliance consulting from a service provider. The relevant distinction is the range of supported tasks, not a promise that every task belongs in one engagement.
Start with your business model, country of residence, intended jurisdiction and existing documents. Ask for a written scope separating company formation, business tax identification, personal tax identification and return preparation.
Where the service shines
- Formation and tax IDs: The stated services cover company formation alongside EIN and ITIN assistance.
- Non-resident focus: The business description specifically addresses entrepreneurs setting up outside their country of residence.
- US and UK options: You can discuss either jurisdiction without assuming that a US LLC is always the answer.
- Compliance consulting: Tax questions can be addressed separately from the act of registering a company.
Where the service falls short
- Hiring an adviser does not transfer your legal responsibilities as an owner or director.
- A service engagement cannot guarantee government acceptance, banking access or a particular tax outcome.
- Formation, an EIN, an ITIN and tax returns are distinct deliverables. You must establish which ones the engagement covers.
| Decision point | This alternative | LLC Founder comparison question |
|---|---|---|
| Jurisdiction | US and UK formation services are stated | Does the proposed engagement cover your chosen jurisdiction? |
| Tax identification | EIN and ITIN services are stated | Which business or personal applications are included? |
| Tax compliance | Non-resident tax compliance consulting is stated | Does the scope include advice, preparation, submission or a combination? |
| Responsibility | Owner supplies accurate facts and meets obligations | Who handles each task after formation? |
Best for: You want professional help connecting formation with the tax identification and compliance questions that follow it.
Verdict: Buy advisory support when your brief includes more than registering the company.
2. Direct government filing: best for hands-on founders
Direct filing means dealing with the formation authority and tax authority yourself. For a US LLC, that involves the relevant state authority and, when required, the IRS; for a UK limited company, it involves Companies House and the relevant HMRC obligations.
This is an alternative to hiring a filing intermediary, not an exemption from local requirements. You become responsible for understanding instructions, submitting documents and responding to correspondence.
Where direct filing shines
- You control the application and receive its supporting records directly.
- You can separate formation from later tax advice rather than buying assistance you do not need.
- Official instructions let you check application requirements at their source.
Where direct filing falls short
- Government instructions do not replace advice about your individual cross-border position.
- You must identify continuing filings yourself, including requirements triggered by ownership or transactions.
- An incomplete application or misunderstood instruction remains your problem to resolve.
| Decision point | Direct filing | LLC Founder comparison question |
|---|---|---|
| Submission | You prepare and submit applications | Which applications does the provider prepare and submit? |
| Interpretation | You interpret instructions or hire separate advice | Is tailored advice included? |
| Correspondence | You track and answer authority requests | Who responds when an authority asks for clarification? |
Best for: You understand the filing requirements and have time to maintain records and follow correspondence.
Verdict: Buy only the advice you need; hold off on a filing service if you can handle submission accurately yourself.
3. A cross-border tax adviser: best for an existing company
An independent cross-border tax adviser is the relevant alternative when you already have an entity and need to establish its tax treatment. Your question might concern owner transactions, US reporting, UK obligations or how company income interacts with your country of residence.
Choose by the adviser's stated qualifications and jurisdictions covered. Do not assume that familiarity with company registration proves competence in every tax system affecting you.
Where specialist advice shines
- The engagement can focus on your existing entity rather than another formation.
- You can request analysis of specific transactions and filing responsibilities.
- You can distinguish the company's obligations from your personal obligations.
Where specialist advice falls short
- Tax advice does not automatically include formation or administrative filings.
- A specialist in one jurisdiction does not automatically cover your home country.
- You still need clear responsibility for submitting returns and retaining records.
Best for: You already own a company and need a documented tax position or filing plan.
Verdict: Buy specialist advice before changing entities to solve a tax question.
Match the provider to the actual application
Before comparing LLC Founder alternatives in 2026, separate these tasks. They use different applications and solve different problems.
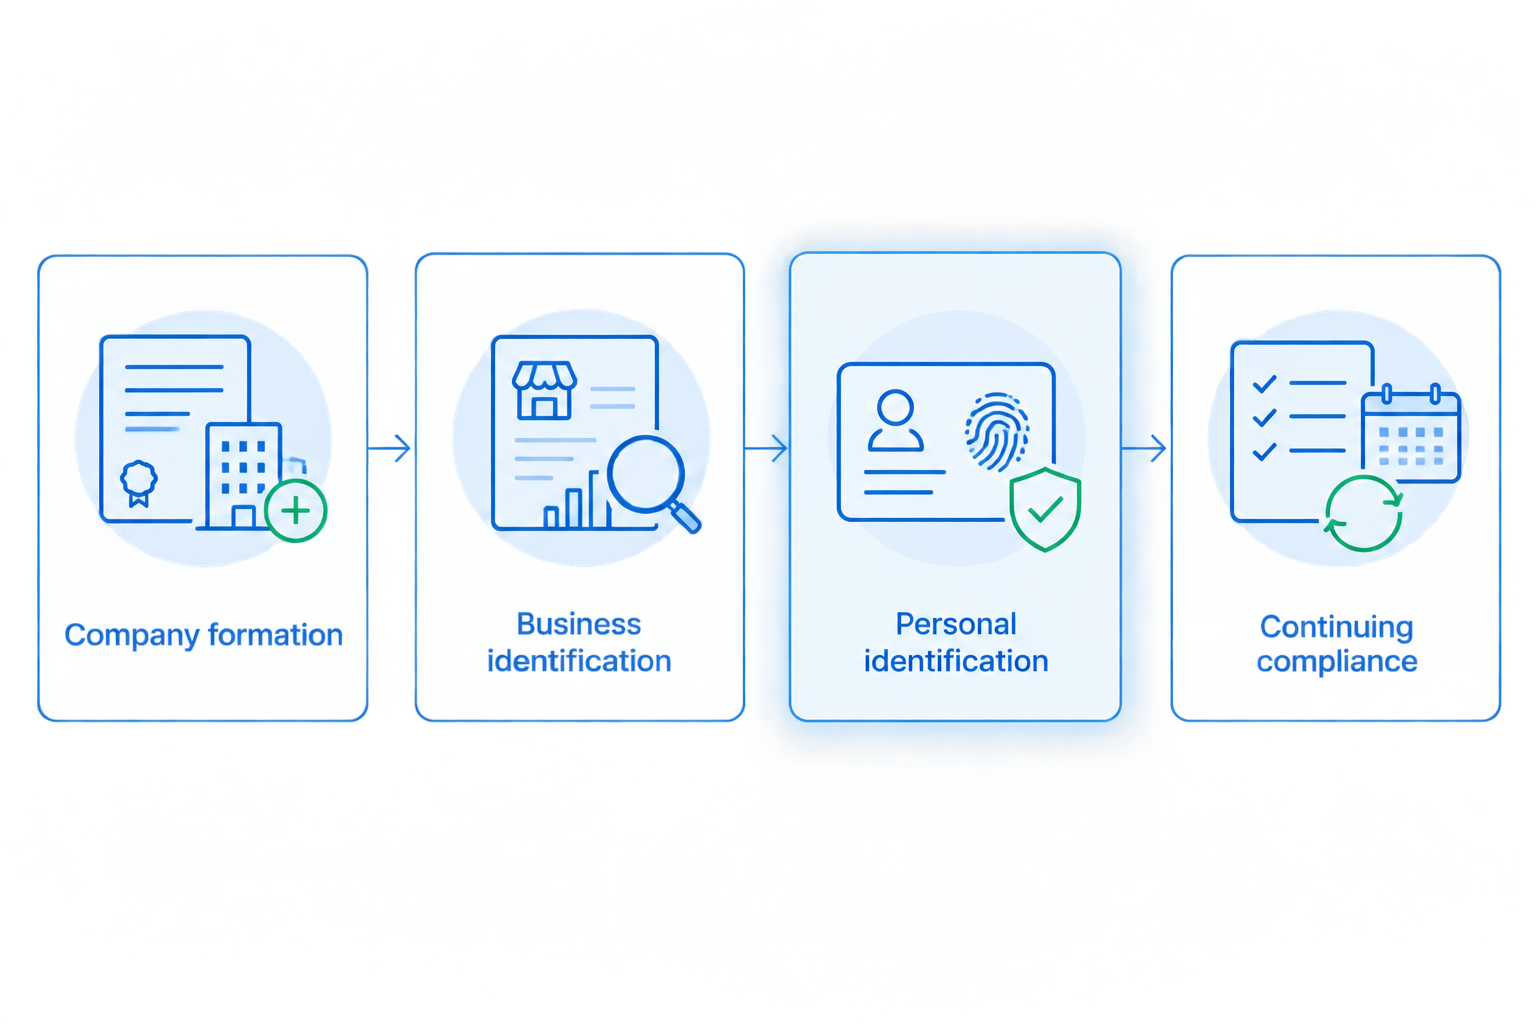
Company formation
A US LLC is formed under state law. State requirements vary, including registered-agent and continuing filing requirements. A registered agent receives specified legal documents; that role is not the same as bookkeeping or tax preparation.
A UK private limited company is registered with Companies House. It needs a qualifying registered office address in its jurisdiction of incorporation, and directors have continuing filing responsibilities. A director does not generally need to live in the UK, but overseas residence does not remove those responsibilities.
Business identification
An EIN identifies a business for US federal tax purposes. The IRS application is Form SS-4. An EIN is not a personal tax number and does not, by itself, establish that a company has satisfied its tax filing obligations.
An international applicant without an SSN or ITIN should follow the applicable IRS application instructions rather than assume the online route is available. The filing method matters.
Personal identification
An ITIN is a US tax processing number for certain individuals who need a US taxpayer identification number but are ineligible for an SSN. The application uses Form W-7, and eligibility depends on a federal tax purpose or an applicable exception.
An EIN does not replace an ITIN. An ITIN also does not provide immigration status or work authorization. For renewals, establish whether renewal is required for the return you intend to file rather than submitting automatically.
Continuing compliance
Formation and identification are not tax returns. Depending on the facts, a foreign-owned US entity can have reporting duties even when the owner expects no US income tax liability.
For example, certain foreign-owned US disregarded entities must file Form 5472 with a pro forma Form 1120 when reportable transactions occur. A disregarded entity is an entity generally not treated as separate from its owner for federal income tax purposes; that treatment does not eliminate every reporting requirement.
For your 2026 decision, the official references are the IRS Instructions for Forms SS-4, W-7 and 5472, the applicable state formation authority, and Companies House guidance on setting up and running a limited company. Use the instructions applicable to the relevant application or tax period.
Why people switch from LLC Founder
A sound reason to switch is a mismatch between the work you now need and the work your existing engagement covers. That is a scope decision, not evidence that LLC Founder provides poor service.
Your jurisdiction changed
If your question has shifted from US formation to a UK company, reassess the provider against UK registration and continuing compliance requirements. Choosing among Commitbiz alternatives raises the same underlying decision: establish the jurisdiction and required work before comparing formation intermediaries.
For a non-resident online founder, the jurisdiction decision should come before the provider decision. Explain where you live, where you perform work and how the business operates before requesting a formation recommendation.
Your company exists, but the tax work remains
An existing formation certificate changes the brief. You might need an EIN application, an ITIN eligibility assessment or a return prepared—not a replacement entity.
Give the next adviser your formation documents, prior applications, authority correspondence and transaction records. Ask which work can continue using the existing company before authorizing another formation.
The written scope is unclear
Vague package descriptions make comparisons unreliable. Use the LLC formation quote inclusions and exclusions guide to structure questions about submission, correspondence, documents and continuing work.
Any Corpulate service fee should be described as a one-time cost for the stated engagement, separate from government fees and future filing obligations. A one-time formation service fee does not make future compliance disappear.
When staying with LLC Founder is the right call
Stay with LLC Founder if the written engagement covers your required work and responsibility for each step is clear. Switching providers has no inherent compliance benefit.
Before moving, establish what has already been submitted, which documents remain outstanding and who controls the contact details used on applications. Do not authorize duplicate applications simply because another provider has become involved.
In 2026, the practical test is unchanged: can you identify the next required action and the person responsible for it? If the current arrangement answers that clearly, retain it unless your requirements change.
FAQ
What’s the best LLC Founder alternative for a non-resident?
Corpulate is the best fit in this comparison when you need US/UK formation, EIN, ITIN and non-resident tax consulting. Confirm which applications and filings are included in the written engagement.
Can I apply for an EIN without an SSN?
An international applicant can apply for an EIN without an SSN when the applicable IRS requirements are met. Follow the current Form SS-4 instructions and use the appropriate application method rather than assuming online eligibility.
Do I need both an EIN and an ITIN?
Not automatically: an EIN identifies a business, while an ITIN serves an eligible individual’s US federal tax identification needs. Establish your personal filing requirements separately from the company’s requirements.
Can a non-resident form a UK limited company?
A person living outside the UK can generally be a director of a UK limited company. The company still needs a qualifying registered office address and must meet Companies House and applicable tax obligations.
Does a US LLC with no tax due still need to file anything?
A US LLC can have filing obligations even when no US income tax is due. Ownership, tax classification and reportable transactions determine which returns or information filings apply.
Should I renew my ITIN before choosing a formation provider?
ITIN renewal is a separate tax identification question, not a general prerequisite for choosing a formation provider. Check your ITIN status and the applicable IRS renewal rules against the return you intend to file.
Does changing formation providers guarantee a business bank account?
No formation provider can guarantee a bank’s approval. Banks and payment platforms apply their own eligibility, identity verification and business review requirements.
One last thing
Before buying another formation package, inventory the company documents you already have. Your next step might be obtaining a missing tax ID or correcting a filing responsibility—not starting over.
For a 2026 handover, request copies of submitted applications, acceptance documents and unresolved correspondence. A clean record makes the next engagement specific.
Related guides
- EIN filing services for foreigners without an SSN
- ITIN application services for non-residents
- UK company formation services for non-residents
Author: Hassaan Ullah Khan, IRS CAA.
Official sources