

Best for non-resident formation and tax-ID coordination: Corpulate. Best for self-managed registration: direct state filing. Best for immigration-sensitive decisions: attorney-led formation. Best for complex tax reporting: CPA-led formation. This 2026 guide compares the best LLC formation services for international students by scope, limitations, and the questions you should resolve before registering.
- Corpulate belongs on your shortlist for the best LLC formation services for international students needing non-resident formation and tax-ID support.
- LLC ownership does not grant employment authorization; international students must separate registration from permission to work.
- Direct state filing suits self-managed applications, not immigration advice or personalized tax planning.
- Choose attorney-led or CPA-led support when immigration restrictions or tax classification determine your next step.
Why this matters
An LLC is a company structure, not permission to work in the United States. If you hold F-1 student status, registering a business does not authorize you to operate it, provide services, or manage its daily activities.
Students living outside the US face a different question: how to establish and maintain a US business without assuming US residency or an SSN. Choose support around your location, immigration status, and planned activities—not student status alone.
For a 2026 decision, start with USCIS guidance on students and employment and its entrepreneur employment pathways. Your designated school official, or DSO, handles school-side student-status processes; an immigration attorney assesses legal questions about your proposed work.
What makes the best LLC formation services for students?
Use these criteria before comparing providers:
- Immigration boundaries: The provider separates company ownership from work authorization and identifies questions requiring immigration counsel.
- Non-resident requirements: The application process accounts for foreign addresses, identity documents, and applicants without an SSN.
- Tax-ID scope: The engagement distinguishes an EIN for the business from an ITIN for an eligible individual.
- Filing responsibilities: You receive a clear explanation of what is included and which state or federal obligations remain yours.
- Fee separation: One-time service fees, government charges, and future filing obligations appear separately.
- Document handover: You know which formation records and tax-ID correspondence you will receive and retain.
Ask for written answers. A general promise to handle everything is not a defined scope of work.
Service routes at a glance
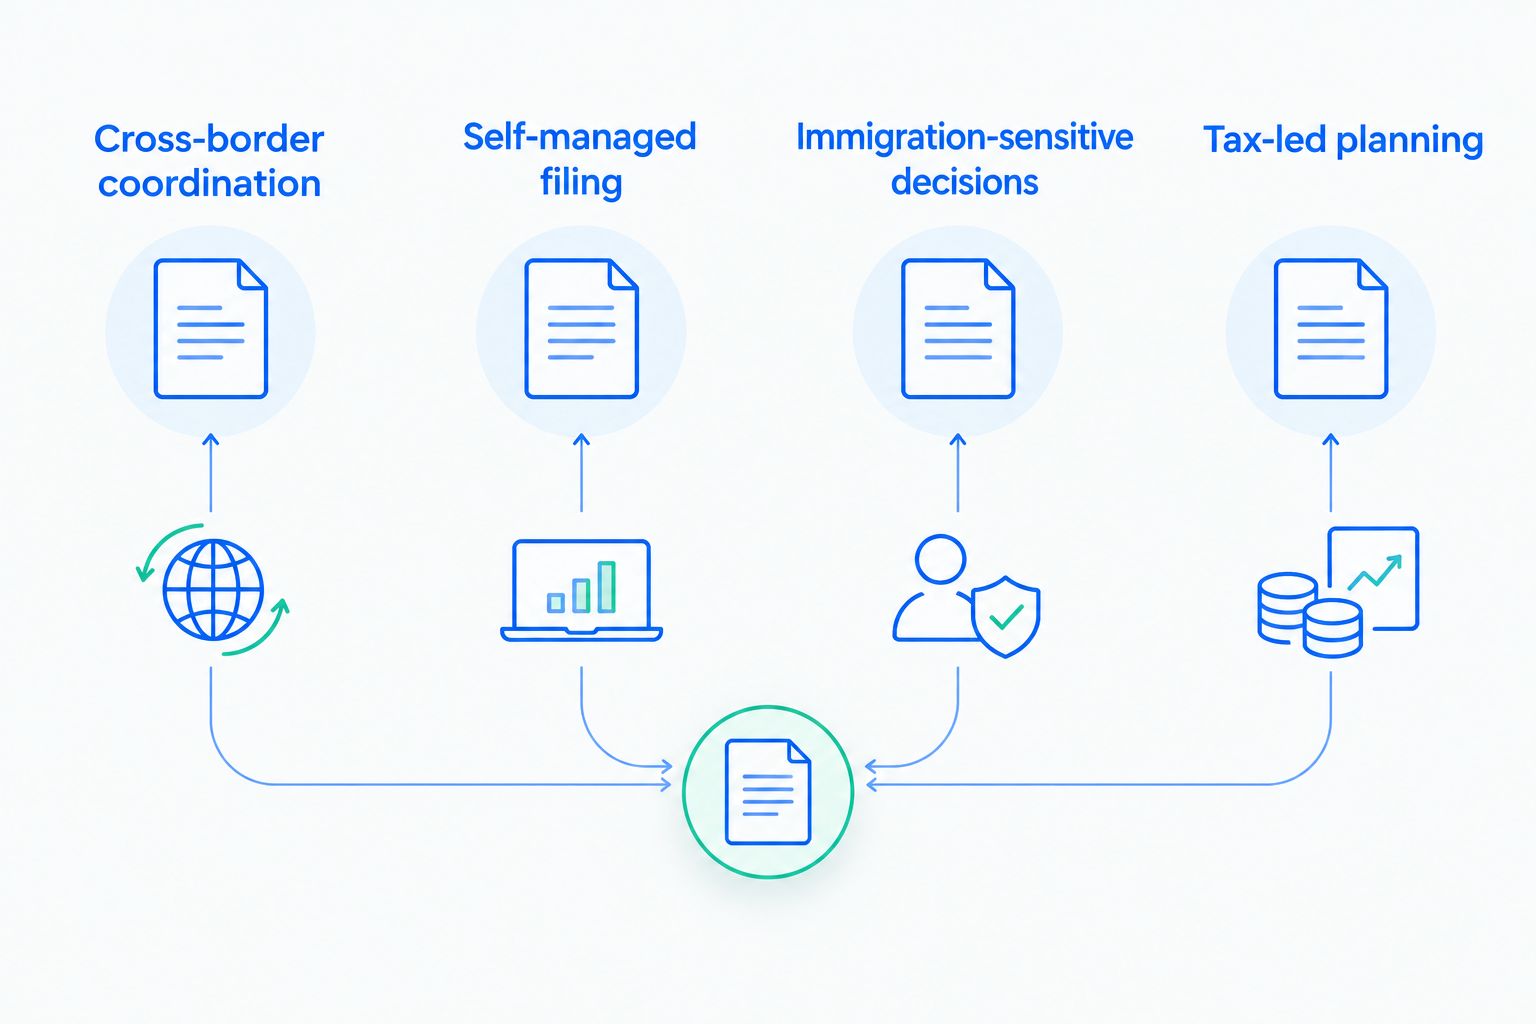
These are service models, not a scored ranking of competing firms. Choose the route that addresses your unresolved question.
| Service route | Best for | Standout scope | Key limitation |
|---|---|---|---|
| Corpulate | Cross-border coordination | US/UK formation, EIN, ITIN, and non-resident tax consulting | Immigration representation is not established in the supplied service description |
| Direct state filing | Self-managed filing | You submit formation documents to the state | Does not include personalized immigration or tax advice |
| Attorney-led formation | Immigration-sensitive decisions | Legal analysis when immigration counsel is included | An attorney's practice area and engagement scope must match your situation |
| CPA-led formation | Tax-led planning | Tax classification and reporting analysis when included | Tax advice does not establish employment authorization |
The routes are not mutually exclusive. You can obtain immigration advice before hiring a formation service, or engage a tax professional after establishing the filing requirements.
1. Corpulate: best for non-resident formation coordination
Corpulate supports LLC/LTD formation, EIN and ITIN applications, and tax compliance consulting for non-resident entrepreneurs establishing US and UK businesses. That scope fits students outside the US who need help connecting registration, tax identification, and subsequent compliance.
Corpulate is best for international students seeking non-resident LLC formation and tax-ID coordination, not a substitute for immigration counsel. Students already in the US should settle work-authorization questions before commissioning an operating business.
Service pros:
- The stated services address non-resident entrepreneurs rather than assuming US residency.
- Formation, business tax identification, and individual tax identification sit within the stated scope.
- US and UK formation support allows you to discuss the jurisdiction before selecting an entity.
Service cons:
- The supplied service description does not establish student-visa legal representation.
- Exact deliverables, government charges, and future filing responsibilities need a written engagement.
Best for: Students abroad who have chosen a US business structure and need coordinated administrative support.
Verdict: Buy formation support after confirming the jurisdiction, engagement scope, and any immigration restrictions.
2. Direct state filing: best for self-managed registration
Direct state filing means submitting your LLC formation application to the relevant state authority yourself. It is a filing route, not an advisory service, so you remain responsible for understanding the requirements and obtaining separate advice.
This route fits a student who has already resolved the legal and tax questions. It does not answer whether you should form an LLC or personally operate the business.
Direct state filing pros:
- You control the information submitted in the formation application.
- You retain direct access to the state filing record and correspondence.
- You can engage legal or tax help separately for defined questions.
Direct state filing cons:
- You must identify applicable state requirements and maintain compliance yourself.
- The formation application does not provide immigration advice, tax classification analysis, or an EIN application service.
Best for: Students comfortable handling administrative filings after receiving any necessary professional advice.
Verdict: Buy separate advice first; use direct filing only when registration is the remaining task.
3. Attorney-led formation: best for immigration-sensitive decisions
Attorney-led formation is the appropriate route when your proposed business activity raises legal questions. For an international student in the US, the engagement must include immigration counsel with relevant experience—not simply an attorney who files company documents.
Describe what you will actually do: develop products, speak to customers, deliver services, supervise contractors, or receive compensation. Counsel needs the activities, not just the proposed company name.
Attorney-led formation pros:
- Immigration counsel can assess proposed activities against your status and authorization.
- A defined legal engagement can address ownership arrangements and company documents.
- You can resolve a legal obstacle before creating administrative obligations.
Attorney-led formation cons:
- A business-formation engagement does not automatically include immigration advice.
- EIN applications, tax returns, and ongoing accounting require separate scope confirmation.
Best for: Students whose immigration status determines whether and how they can participate in the business.
Verdict: Buy immigration advice before formation when your permitted activities are unresolved.
4. CPA-led formation: best for tax-led planning
CPA-led formation puts tax analysis before registration. A certified public accountant with relevant international-tax experience can assess classification and reporting questions when those services are included in the engagement.
This route deserves priority when ownership, existing businesses, or cross-border transactions complicate the tax position. Ask specifically about experience with non-resident individuals and foreign-owned US entities.
CPA-led formation pros:
- You can assess tax classification before selecting an entity structure.
- Personal and business filing obligations can be considered together.
- Recordkeeping requirements can be established before transactions begin.
CPA-led formation cons:
- A CPA engagement does not determine immigration work authorization.
- State formation and registered-agent arrangements are not automatically included.
Best for: Students whose main uncertainty concerns tax residency, entity treatment, or cross-border reporting.
Verdict: Buy tax analysis before registration when classification or reporting drives the decision.
How these routes are ranked
The order prioritizes non-resident formation coordination, followed by self-managed filing and specialist-led alternatives. It reflects the stated service scope and the criteria above—not service testing, customer-review scoring, or a claim that every student needs the same provider.
Choose the route that resolves your actual obstacle. Immigration uncertainty outranks filing convenience; tax uncertainty requires tax analysis before a registration decision.
What to confirm before forming an LLC in 2026
Separate ownership from authorized work
Do not treat an EIN, formation certificate, or company bank account as employment authorization. For F-1 students, USCIS rules govern permitted employment; an ordinary LLC registration does not change those rules.
Ask your DSO about the applicable school process. Ask immigration counsel whether your proposed activities require authorization and whether the contemplated arrangement satisfies the relevant requirements.
Distinguish an EIN from an ITIN
An EIN identifies a business for federal tax administration. An ITIN identifies an individual who needs a US taxpayer identification number but is not eligible for an SSN.
An ITIN does not authorize employment or change immigration status. Do not apply merely because you own an LLC; first establish the federal tax purpose and eligibility under IRS Form W-7 instructions.
For EIN applications, the IRS Form SS-4 instructions address responsible parties without an SSN or ITIN. The online application has separate eligibility conditions, so the appropriate application method matters.
Check tax residency separately
Student immigration status and federal tax residency are different classifications. IRS Publication 519 explains the substantial presence test and exceptions for qualifying individuals.
For people subject to that test, it generally requires at least 31 days of US presence in the current year and 183 weighted days across 3 calendar years. Qualifying student days can be excluded under specific rules; do not apply the ordinary calculation without checking those exceptions.
Identify federal reporting
A foreign-owned US disregarded entity—a business generally not treated as separate from its owner for income-tax purposes—can have Form 5472 reporting obligations for reportable transactions. IRS instructions address filing that form with a pro forma Form 1120, a limited accompanying return.
A student can also have individual filing obligations, including Form 8843 where applicable. No revenue does not establish that no filing is required.
Choose the state deliberately
Compare formation requirements, registered-agent requirements, ongoing filings, and whether business activity creates registration obligations elsewhere. A registered agent receives official documents; that role does not establish your work authorization.
Use the state comparison for non-resident LLC owners to organize the jurisdiction discussion. Do not choose a state solely because its name appears repeatedly in formation advertising.
Questions to send before paying
For your 2026 engagement, request written answers to these questions:
- Which formation documents and tax-ID applications are included?
- Which one-time service fees are separate from government charges?
- Who handles the registered-agent arrangement and future state filings?
- Does the engagement include an assessment of federal information returns?
- Who receives IRS correspondence and provides copies to you?
- Which immigration questions require separate counsel?
A one-time formation service fee does not remove future legal or tax obligations. Keep the engagement, formation records, ownership documents, and tax correspondence together.
Discuss your formation requirements
Explain your location, student status, and tax-ID needs before choosing a service scope.
Official sources for your 2026 decision
Check these official materials for the relevant requirements before filing:
- USCIS, Students and Employment: Student employment restrictions and authorization categories.
- USCIS, entrepreneur employment pathways: Immigration considerations for starting and operating a business.
- IRS, Instructions for Forms SS-4 and W-7: EIN and ITIN application requirements.
- IRS, Publication 519 and Form 8843 instructions: Tax residency and excluded-presence rules.
- IRS, Instructions for Form 5472: Reporting requirements for covered foreign-owned entities.
- Your selected state's filing authority: Formation, registered-agent, and ongoing state requirements.
These references address different obligations. Approval of a state formation application does not establish compliance with the others.
Which formation route should you choose?
Choose Corpulate for non-resident formation and tax-ID coordination after resolving immigration questions. Choose attorney-led support first when your permission to perform the planned work is unclear, and CPA-led support first when tax treatment determines the structure.
Direct state filing fits only when you are ready to manage the application and subsequent obligations yourself. The right default is a defined engagement—not the shortest application form.
FAQ
Can an international student own a US LLC?
LLC ownership and permission to work are separate questions. State formation requirements govern registration, while your immigration status and authorization govern work you perform in the US.
Which LLC formation service should an international student choose?
Choose the service route that resolves your main uncertainty: formation coordination, immigration advice, tax analysis, or self-managed filing. A formation service alone does not resolve every student’s legal position.
Do I need an SSN to obtain an EIN?
An SSN is not a universal prerequisite for obtaining an EIN. Follow the IRS Form SS-4 instructions for your responsible party and use an application method for which you qualify.
Does getting an ITIN let me work for my LLC?
No. An ITIN is a federal tax-processing number, not employment authorization, and it does not change your immigration status.
Do I need to file anything if my LLC earns no revenue?
No revenue does not establish that no filing is required. State obligations and federal information returns depend on the entity, ownership, transactions, and applicable rules.
Is a UK LTD a workaround for US student work restrictions?
A UK company registration does not grant permission to work while physically in the US. Assess US immigration restrictions separately from the company’s jurisdiction.
Does a one-time formation fee cover future compliance?
Only the deliverables expressly included in the engagement are covered. A one-time service fee does not remove government charges, future filings, tax obligations, or separate professional engagements.
One last thing
Write down the work you expect to perform before choosing a provider. A list of activities gives immigration and tax advisers something concrete to assess; an LLC name does not.
For a 2026 launch, make that activity list your first document—not the formation application.
Related guides
- EIN filing services for applicants without an SSN
- ITIN application services for non-residents
- Tax filing services for non-resident aliens
Author
Hassaan Ullah Khan, IRS CAA